In four weeks, live agent payments landed in the Netherlands, Ukraine, France, and Mexico. India got its first agentic protocol on UPI. Starling put a scam-checking agent in front of five million customers, and BBVA counted 100,000 employees on ChatGPT Enterprise. Then Washington changed the rules entirely, an export order pulled Anthropic’s newest models from the market mid-month, and regulators set the terms of their return while OpenAI slowed a launch of its own.
And behind all of it, the money moved: Anthropic and OpenAI filed confidential S-1s a week apart, at valuations last reported near $965 billion and $852 billion.
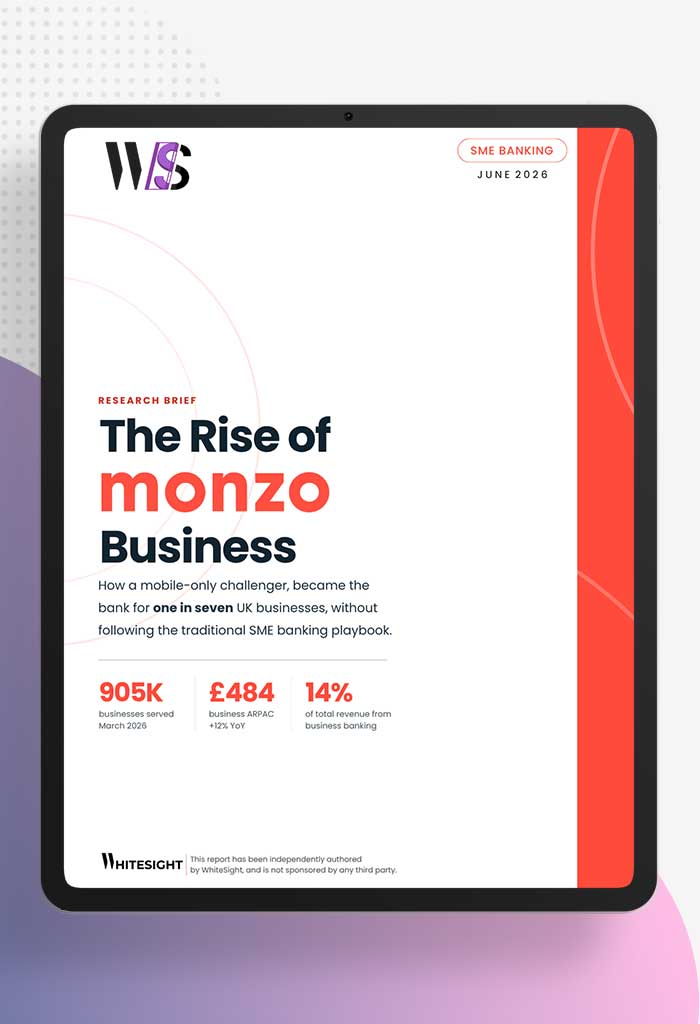
For years, SME banking in the UK moved slower than the businesses it served.Accounts took time to open, fees were hard to decode, and financial admin sat across disconnected tools. For sole traders and SMBs, banking often added friction instead of removing it.And while Monzo did not begin as an SME bank, its business banking rise came after it had built a consumer brand around speed, simplicity, and mobile-first money management. When Monzo brought that playbook to SMEs, it entered a market ready for a cleaner alternative. By 2026, it was serving 905K businesses, roughly 1 in 7 UK businesses.
Is Starling the digital bank that won by behaving like a traditional bank?Starling is NOT the UK’s biggest neobank, but it may be one of its most disciplined. From building a full-stack bank before chasing scale, to using deposits, secured lending, cost control, and Engine by Starling to create a sustainable operating model, Starling offers a different challenger-bank playbook: bank first, app second.
Stripe’s agentic commerce strategy begins with a shift in what software can do. AI assistants are moving beyond writing, searching, and coding. They are beginning to shop, book, pay, invest, and borrow on behalf of users. Once agents begin transacting with real money, every part of finance needs the same foundation. A trusted way for agents to pay. That foundation is where Stripe is making its move.As Visa, Mastercard, Google, Coinbase, OpenAI, Tempo, and others race to define how agent payments should work, Stripe is taking a different route. It has co-authored payment standards, opened them for others to use, and built support for rival protocols through a single integration. The visible standards remain open. The value collects beneath them.
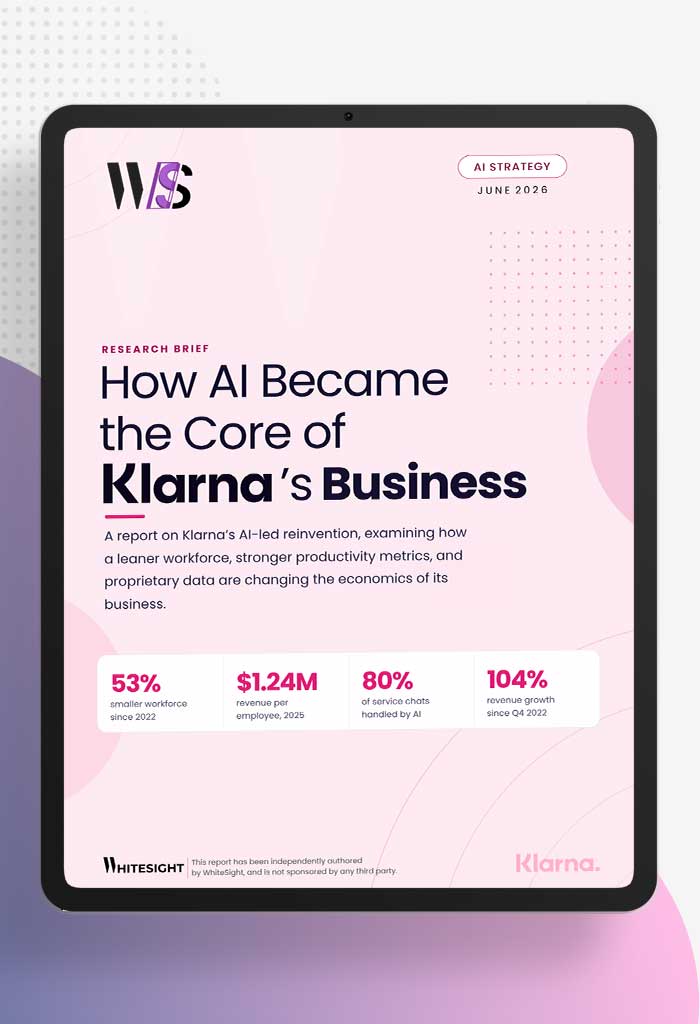
Klarna’s AI story began under pressure.By 2022, the company was operating in a very different market environment. Its valuation had fallen from the highs of the fintech boom, losses were drawing closer attention, and investors were placing greater emphasis on efficiency alongside growth. What followed was one of the most aggressive AI transformations in fintech services.Klarna pushed AI into the core mechanics of the company: customer service, shopping discovery, advertising, credit underwriting, software development, marketing, data analysis, and workforce design. By 2025, it had become a leaner, more technical organization, with revenue more than doubling from Q4 2022 while operating expenses declined.
Adyen is one of those companies that still gets described as a payments processor, even though the business has moved far beyond that label. What began as a single-platform payments stack in 2006 has evolved into a global fintech infrastructure layer spanning acquiring, unified commerce, embedded finance, AI, and platform-led distribution.Adyen avoided the usual payments trap: growing by stitching together local providers, point solutions, and market-specific integrations. Its bet was architectural discipline. Build the stack in-house, keep one global integration, and let every new layer compound on the same core. A single-platform foundation in 2006. Global scaling from 2012. Unified Commerce from 2017. Embedded finance and AI from 2022 onward. Each phase expanded the surface area, but preserved the same underlying logic.
In May 2026, agentic finance moved from isolated proofs into distribution infrastructure. Mastercard took Agent Pay live across Portugal and the Netherlands. Visa expanded Agentic Ready across Asia Pacific and CEMEA, enrolling issuers before agent volume arrives. Stripe, Coinbase, Circle, Fireblocks, MoonPay, and AWS turned crypto and stablecoin rails into usable infrastructure for agent-initiated payments. Banks stopped treating agents as experiments. Fiserv and FIS packaged agent capabilities for bank clients. Lloyds and Citi built internal agent platforms with marketplaces, monitoring, and audit. Robinhood opened brokerage and card rails to customer-controlled AI agents. OpenAI connected ChatGPT to more than 12K+ financial institutions, while Anthropic turned finance agents into off-the-shelf products.
Singapore is often painted as the crown jewel of Asian fintech, highly digital, affluent, and open to innovation. But it is also crowded and highly competitive. While well-funded local consortia built full-scale digital banks and absorbed heavy losses, Revolut took a leaner path. Operating without a full banking licence, the UK challenger grew its Singapore retail customer base by 40% and reached a 15% net profit margin in 2024. That raises a compelling strategic question: how did Revolut capture the highly lucrative Singapore market while capital-heavy digital banks stalled in the red?